Warning on risks: Financial contracts for difference are complex instruments and are associated with a high risk of rapid financial losses due to leverage. On 71.07% of retail investor accounts, financial losses occur when trading financial contracts for difference with this provider. You should consider whether you understand how financial contracts for difference work, and whether you can afford to take the high risk of suffering financial losses. Please read the Risk Disclosures.

Maersk's Profits Are Rising, but a Return via the Suez Canal Could Reduce Margins [1]
In the third quarter of 2026, Maersk posted an operating profit of $3.3 billion, up 155% year-over-year. Higher container shipping rates contributed to the improved performance, although shipping volume declined slightly. However, the gradual return of ships via the Suez Canal may reduce high margins. Shorter routes save fuel and time, while also freeing up shipping capacity and creating room for a decline in freight rates. [2]
About the company
A.P. Møller – Mærsk is a Danish shipping and logistics group headquartered in Copenhagen, whose shares are traded on the Nasdaq Copenhagen stock exchange. It provides container shipping, logistics services, and port terminal operations. In this way, it integrates the transport of goods by sea with warehousing and delivery to the customer. The individual business segments have different profit margins and varying sensitivity to changes in freight rates, which affects the financial stability of the entire group.
New outlook aligns with analysts’ expectations
Maersk’s revenue rose 27% year-over-year to $18.1 billion. Earnings before interest, taxes, depreciation, and amortization (EBITDA) increased by 75% to $4.71 billion, though it fell short of the average analyst estimate in the LSEG survey by approximately 6.5%. The company also raised its full-year adjusted EBITDA outlook from $10.5 billion to $12.5 billion to $14 billion to $14.5 billion. Analysts had already anticipated $14.02 billion. [3] The new outlook thus largely confirmed their expectations, although it represented a significant improvement over management’s previous estimate. On November 5, the day the results were released, Class B shares closed at 20,870 DKK, marking a daily decline of 5.99%.*
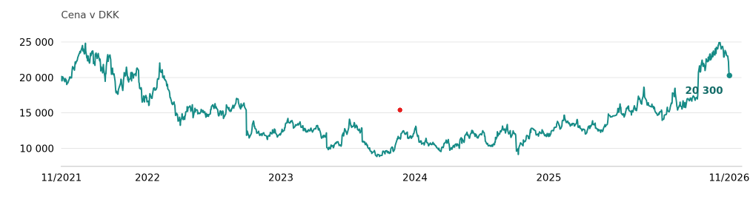
Maersk Class B Share Price Performance Over the Past Five Years*
Higher rates offset rising costs
The biggest improvement came from ocean freight. The average rate achieved rose by 46% to $3,287 per unit equivalent to a 40-foot container, while the volume transported fell by 0.8%. Unit costs, adjusted for constant fuel prices, increased by 4.8%. The Ocean division’s operating margin rose from 6.2% to 20.6%, primarily due to higher rates. Operating profit was also supported by an extension of the estimated useful life of vessels from 20 to 25 years, which reduced quarterly depreciation by $176 million. This accounting change did not, in and of itself, increase cash generation. The results therefore do not yet provide evidence that Maersk can achieve similar margins even with lower-cost shipping. To maintain them, it would need to reduce per-container costs accordingly. [4]
Suez may lower operating and shipping costs [5]
Pressure on rates may intensify as shorter routes are gradually reinstated. On November 2, Maersk and Hapag-Lloyd announced the return of their joint ME1 service between India and Europe via the Suez Canal instead of circumnavigating Africa. The same volume of cargo can thus be transported in less time and with less shipping capacity required. The freed-up vessels may increase shipping capacity and intensify price competition. Fuel cost savings may then outweigh the decline in revenue caused by lower rates. However, further route changes remain contingent on the security situation in the Red Sea. [6] On November 5, the Drewry WCI freight rate index fell 1% week-over-week to $4,389 per 40-foot container, though it remained 124% higher than a year ago. This movement so far indicates only a slight decline from high levels and does not, in and of itself, confirm a sustained turnaround in the market.
Maritime shipping continues to drive profit growth
Logistics services and terminals provide Maersk with additional sources of revenue, but their contribution to operating profit remains significantly smaller. In the third quarter, they generated a combined $752 million, while the ocean shipping division reached approximately $2.6 billion. Furthermore, according to calculations based on the published results, Ocean accounted for approximately 94% of the group’s year-over-year EBITDA growth. Thus, maritime transport continues to drive most of the improvement. The development of other services is expanding Maersk’s business, but so far it has not significantly reduced the dependence of its profit growth on freight rates. Therefore, when valuing the stock, the decisive factor remains what portion of current maritime margins the company will be able to maintain once capacity constraints are eased. [7]
Cash flow must also cover fleet renewal
Strong financial performance translated into free cash flow of $2.389 billion for the third quarter. As of the end of September, Maersk had a net cash position of $3.213 billion, even after accounting for lease obligations. This reserve provides the company with the flexibility to finance operations during slower periods. However, the company plans capital expenditures of $10 to $11 billion over the two-year period 2026–2027, so it will need part of the cash generated for asset renewal and development. The dividend policy calls for paying out 30 to 50 percent of adjusted net income, though the specific dividend amount also depends on the outlook and investment needs. It is therefore crucial for shareholders to know how much cash will remain after investments, even in years with lower shipping rates. [8]
Conclusion
Maersk is currently profiting significantly from the limited availability of shipping capacity. A return to the Suez route could erode this advantage even amid continued growth in global trade. When valuing the stock, it therefore makes more sense to base the assessment on profitability at lower freight rates than to assume that the current margin will persist. A more sustainable improvement in financial performance would be confirmed by declining unit costs and the ability to finance both investments and dividends even amid weaker freight rates. As long as profit growth is driven primarily by higher rates and container costs are rising, an exceptionally strong quarter does not provide a reliable basis for estimating long-term performance. [9]
This text constitutes marketing communication. It does not constitute any form of investment advice or investment research, nor is it an offer to engage in any transaction involving a financial instrument. The content of this text does not take into account the individual circumstances of readers, their experience, or their financial situation. Past performance is not a guarantee or prediction of future results.
* Past performance is no guarantee of future results.
[1] – [9] Forward-looking statements are based on assumptions and current expectations, which may be inaccurate, or on the current economic environment, which is subject to change. Such statements are not a guarantee of future performance. They involve risks and other uncertainties that are difficult to predict. Actual results may differ materially from those expressed or implied in any forward-looking statements.
O.Z.I. Online Zone Investment Opportunities (OZIOS) is a registered trademark of APME FX TRADING EUROPE LTD, a Cyprus Investment Firm (CIF) supervised and regulated by the Cyprus Securities and Exchange Commission (CySEC) under CIF license number 335/17, with a registered address at Lophitis Business Center, Office 404, 4th Floor, 28 October Ave 249, Limassol 3035, Cyprus. Contracts for Difference (CFDs) are complex instruments and carry a high risk of rapid financial loss due to leverage. 71.07% of retail investor accounts lose money when trading CFDs with this provider. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
[1] Maersk – Company Profile and Stock Information. Nasdaq Copenhagen.
[2] Maersk – Q3 2026 results. Reuters – analyst estimates, November 5, 2026. Tradzy – closing price of Class B shares, November 5, 2026.
[3] Yahoo Finance – MAERSK-B.CO, daily closing prices from November 8, 2021, to November 6, 2026; chart created by the author.
[4] Maersk – Interim Financial Report for Q3 2026, Ocean Division and Note 5 on the change in depreciation estimates.
[5] Maersk – Return of the ME1 route via the Suez Canal, November 2, 2026. Drewry – World Container Index, November 5, 2026.
[6] Maersk – Q3 2026 results; author’s calculation of the Ocean division’s share of year-over-year EBITDA growth: (3,699 − 1,787) / (4,710 − 2,686) = 94.47%.
[7] Maersk – Q3 2026 financial report, cash position, and investment outlook. Capital and dividend policy.
[8] OZIOS – current risk warning on the homepage; proportion of loss-making accounts 71.07%, verified on November 9, 2026.